



Price comparison site Moneysupermarket, wealth manager Brooks Macdonald and retailer Frasers are three companies that the market has wrongfully marked down, according to three UK fund managers.
All come with concerns including how AI will impact business models, stalling growth and even questions surrounding the reputation of its founder. Yet the pricing of these stocks might have been judged too harshly, according to some.
The phenomenon isn’t limited to these names either. According to Will Tamworth, manager of Artemis UK Smaller Companies and Artemis UK Future Leaders, the median company across his fund trades on a price-to-earnings (P/E) ratio of 10x, has a free cash flow yield of nearly 9%, is producing double-digit earnings growth and has no net debt.
“If we found that median company, we would be arguing it was about 50% mispriced,” he said. “That’s the scale of the mispricing we see in the UK market.”
Moneysupermarket
Tamworth’s main example was Moneysupermarket, which owns the MoneySavingExpert website. It is the market leader in price comparison, has no net debt and a free cash flow yield close to 10%. Its Savings Club has 2.5 million members, which the manager said turns a one-off search each year into repeat business.
While investors fear that AI assistants such as ChatGPT will take over the job of comparison sites, Tamworth disagreed.
“The reason we don’t think it does get disrupted is that it’s a regulated business,” he said. “It has links into all the insurance companies. Amazon tried to come into this market three or four years ago but exited a year later, having never built up that panel of insurers.”
It might also be that AI chatbots are a solution to a problem that doesn’t exist.
“You can already go to Moneysupermarket and get 300 quotes in 30 seconds. What’s the advantage of using a bot or an agent to do that for you?”, he asked.
“And why would the insurers give links to the agents when they know that the person is going to switch the second a cheaper insurance product becomes available, when most of them make money out of that unwillingness to switch at the first possible moment?”
Performance of stock over 1yr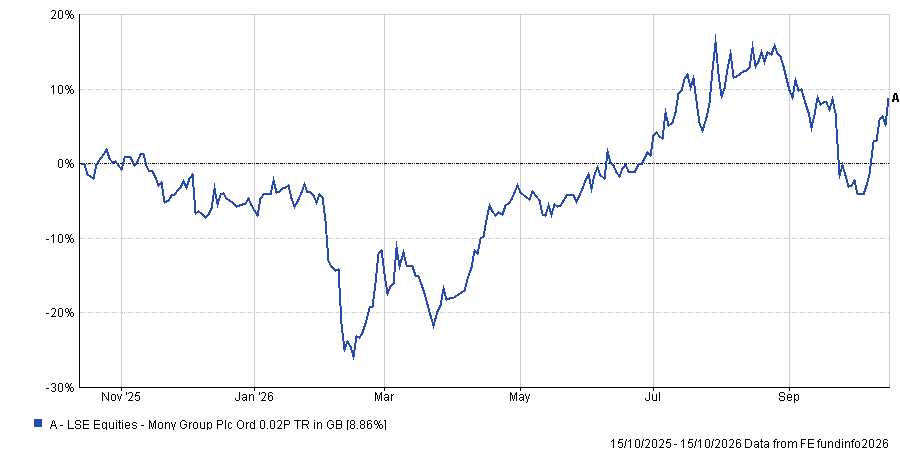
Source: FE Analytics
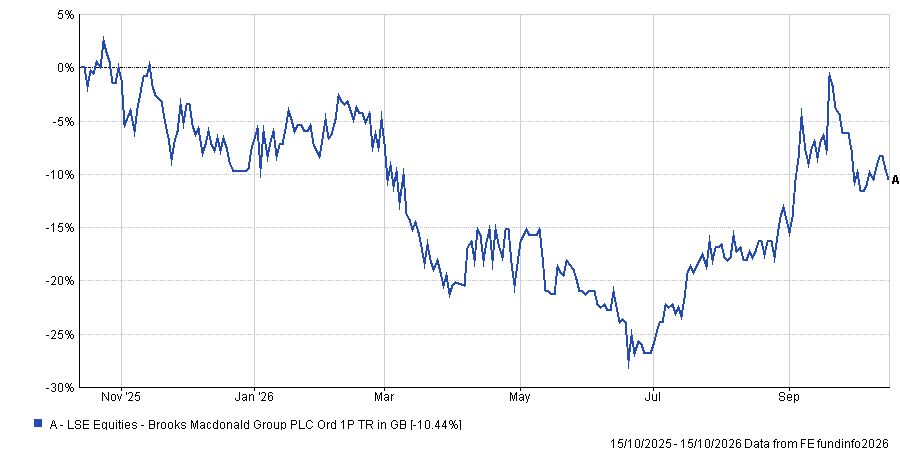
Brooks Macdonald
Ken Wotton, manager of the Strategic Equity Capital trust, chose Brooks Macdonald, a UK wealth manager and financial adviser. The market rates it as a business with no growth, at about 7x operating earnings (profit from running the business before interest and tax). Wotton said deals for UK wealth managers in recent years have mostly priced them at 12x to 18x.
Chief executive Andrea Montague joined as finance director and has run the company for two years. Wotton said she has spent that time fixing the business.
“She’s done a lot of heavy lifting to try and improve and transform the business to put it into a position where it can resume growth, which has stalled,” he said. “The market is not yet believing that.”
Brooks Macdonald has now reported three consecutive quarters of growth, Wotton noted, predicting a re-rating if that continues, followed by upgrades to profit forecasts.
But if that doesn’t happen, he said a takeover is a likely outcome, with private equity already active in the sector.
Wotton holds about 25% of the company across the funds he manages (he is lead manager of WS Gresham House UK Microcap, WS Gresham House UK Smaller Companies and Strategic Equity Capital, and co-manager of the Baronsmead Venture and Second Venture trusts, as well as WS Gresham House UK Multicap Income).
This, he said, would be enough to block a special resolution, the type of vote that needs a supermajority.
“It’s highly unlikely that, whether it’s private equity or corporate, anyone will try to buy that company without us agreeing to it,” he said. “So we can effectively stop a takeover at a premium to a depressed price, or we can enable one at the right price.”
Performance of stock over 1yr
Source: FE Analytics
Frasers
Finally, Gareth Channon, manager of Aurora UK Alpha, picked Frasers, the retail group run by Mike Ashley. He said investors have struggled to look past Ashley’s public image and miss the financial record underneath.
“It’s a discount retailer, which is a terrible business to be in,” Channon said. “But just stand back and look at the record, look at the machine underneath, and he earns over 15% return on his capital. And he’s not good at articulating what he’s done, so you have to trust him on his record.”
Channon said the shares trade at less than half what the business is worth, and Frasers also owns 11 million square feet of property, which Channon said protects the downside. On top of that, Frasers is almost the only group buying UK retail property and recently took control of the luxury brand Boss.
“When you own the whole shopping centre, not only do you decide where your shops go, but you also have all your competitors trading,” the manager said. “So it’s a very advantageous position for these groups.”
Performance of stock over 1yr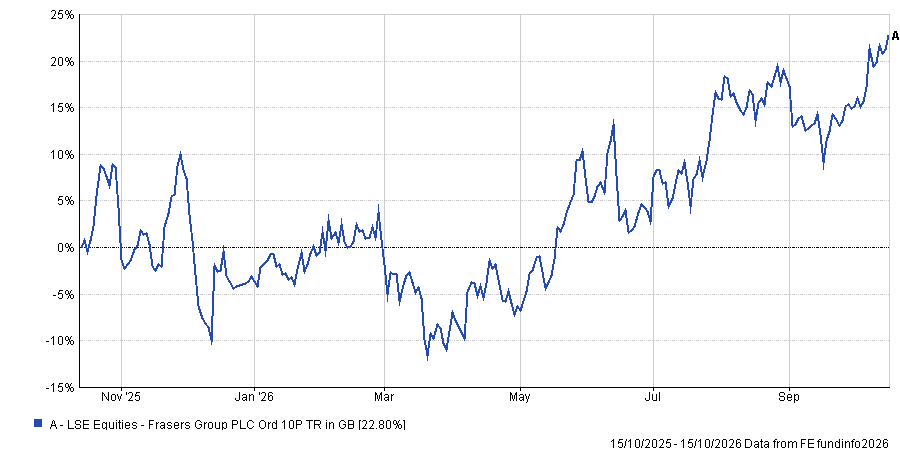
Source: FE Analytics